

Four | Buy Now, Pay Later
Four Technologies, Inc
- 4.5
- 4.21K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
Four | Buy Now, Pay Later Pros and Cons
Pros
- Flexible payment plans for budgeting
- No interest on timely payments
- Easy approval process
- User-friendly interface
- Wide range of partner stores
Cons
- Late fees for missed payments
- Limited to certain regions
- Requires credit check
- Not suitable for large purchases
- Potential to overspend
 Analysis by All-app
When I first tried Four, the appeal was easy to understand: it gives online shoppers another way to manage the timing of a purchase. I can see why a pay-later app feels useful during a first week of browsing, especially when a planned expense lands before payday. The important question, though, is whether splitting a bill makes it easier to handle—or simply makes spending feel smaller than it is. I would treat Four as a payment tool, not extra money.
Where the first-week appeal comes from
Four is a free finance app from Four Technologies, Inc. Its focus is online shopping and flexible payment timing, so it is most relevant when a retailer offers Four at checkout and a purchase does not fit comfortably into one immediate payment. The app is rated for Everyone, and it has an average rating of 4.5 from around 9,900 ratings, with more than 500,000 installs. Those figures suggest that it has found an audience, but they do not tell me whether a particular purchase is sensible for you.
The first-week benefit is practical rather than mysterious: a shopper can consider a purchase now and spread its cost instead of paying the whole amount at once. That can be helpful for a necessary replacement, such as a household item that has stopped working, if the payment schedule fits money you already expect to have. It is less compelling for an impulse buy. Before choosing a split-payment option, I would ask myself whether I would still make the purchase if I had to pay the full cost today.
A checkout routine that keeps the decision grounded
A useful habit is to decide on the item and its maximum acceptable total before reaching checkout. Then check the payment terms shown for that particular transaction and compare the scheduled amounts with your actual budget. I would not rely on a small instalment to judge affordability: the full purchase still belongs in your spending plan, and other scheduled payments may be due at the same time.
For a realistic example, imagine that a needed accessory breaks shortly before payday. If replacing it cannot wait, Four may help divide the outlay into planned payments rather than forcing one larger payment immediately. I would still check that the first payment and later instalments leave room for essentials such as food, rent, and transport. If the purchase can wait until the next pay cycle, saving for it may be simpler and leave fewer obligations to track.
That distinction is where the app’s usefulness depends on the user. Four can help organize when a purchase is paid for; it cannot make an item less expensive or make an uncertain future budget reliable. I would use it for a considered need more readily than for a treat that only feels affordable because the checkout total has been divided.
What changes from month to month
After the novelty wears off, the value of a payment app comes down to whether it fits into a repeatable routine. Four is most useful if you already shop online and can check upcoming commitments before placing another order. A quick review of what is due, alongside regular bills and everyday spending, helps prevent several individually manageable purchases from becoming a difficult month.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
That review is worth doing before checkout, not just after a reminder arrives. I would keep a simple note or budget entry for each purchase and its payment dates, especially if I use more than one pay-later service. The non-obvious trade-off is that convenience can spread payment obligations across several places. A single app may show its own activity, but a household budget needs to account for every commitment, not only the one currently on screen.
Compared with paying by debit card, Four may soften the immediate impact on a bank balance, but debit gives a clearer sense of money already spent and does not leave instalments to remember. A credit card may be more familiar for frequent purchases, though it brings its own repayment choices and risks if a balance is carried. Saving first is slower, but it avoids adding a future payment. I would choose between these options based on the purchase and my ability to keep track, rather than assuming one method is always best.
Maintenance, reminders, and the points to check
The app is currently version 1.17.25 and requires Android 6.0 or later. That makes the Android compatibility question straightforward for someone using an older phone: check the device’s operating system before expecting to install it. The app is also free to download, but that should not be confused with every purchase being cost-free under every possible circumstance. Read the terms presented for the individual checkout and make sure you understand the schedule before confirming.
Payment reminders can be useful, but I would treat them as a backup rather than the whole system. Notifications can be missed, muted, or buried among other alerts. A stronger routine is to note the payment dates somewhere you already check and keep enough money available before each one. If your income varies, or your essential bills already leave little margin, a future payment date may be harder to manage than it looks at checkout.
Before relying on Four for an order, I would also check that the retailer offers it for that purchase and that the terms displayed match what I can afford. Availability at one checkout does not mean it will be available for every shop or item. If an order is delayed, changed, or returned, keep the retailer’s confirmation and check how the payment arrangement is handled. The useful principle is to follow both the merchant’s order status and the app’s payment information rather than assuming one automatically updates the other.
There is also a maintenance cost in attention. Every split purchase creates something to remember, even when the app makes the process feel simple. If you make frequent small orders, those obligations may become more annoying than helpful. I would set a personal limit on how many purchases I am willing to have outstanding at once, or use Four only for purchases that are planned and easy to identify later.
When the convenience starts to wear thin
The main source of fatigue is not necessarily the app itself; it is the growing number of payment dates competing for attention. A shopper who checks out often may lose the clear connection between an item and the money still owed for it. That makes a payment calendar or spending note more valuable than another round of browsing. If tracking feels like work, returning to one-payment purchases may be the better choice.
I would skip Four if I am using it to stretch a budget that is already short, if I cannot predict whether I will have money available for later payments, or if I tend to forget financial deadlines. It is also not a substitute for emergency savings. For a non-urgent purchase, waiting and setting money aside can offer more control; for a necessary expense, comparing the full cost and payment terms remains important.
Readers often want to know whether the app is free and whether every transaction works the same way. The app itself is free, but the terms shown for a specific order are what matter when deciding how much is due and when. They should be checked each time rather than inferred from a previous purchase. Another practical question is whether the app is right for an occasional shopper: it can be, if a supported online checkout and a clear payment plan solve a real timing problem. If you rarely shop online, a regular card or saving first may be simpler.
For anyone comparing alternatives, I would focus on the total obligation, the dates, and the amount of account management each option demands. A card payment can keep records in one familiar place, while a pay-later app may make a particular checkout easier to divide. Neither advantage makes a purchase automatically affordable. If the choice is between splitting a want and postponing it, postponing gives you the cleanest answer about whether it belongs in your budget.
Four has an average rating of 4.5 and around 4,200 written reviews, but popularity is only one part of a decision about borrowing or delaying payment. I would use it selectively, read each transaction’s terms, and review the combined effect of all upcoming payments. Its lasting value depends less on how quick the first checkout feels and more on whether it helps you stay deliberate after several weeks of ordinary spending.
What’s the Buzz with Four?
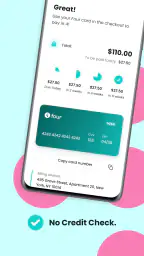
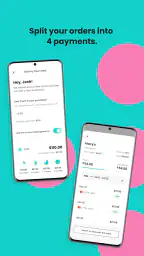
So, what exactly is Four | Buy Now, Pay Later? In a nutshell, it’s an app that allows you to split your purchases into four interest-free payments. This isn’t just a lifesaver for those unexpected expenses but also a game-changer for budgeting aficionados. Imagine snagging that must-have gadget or those killer shoes without the immediate financial pinch.
Getting Started with Four
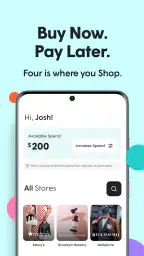
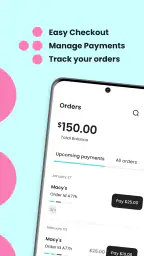
Getting started is as easy as pie. I downloaded the app from the App Store, and the interface immediately struck me as clean and user-friendly. After a quick sign-up process, I was ready to dive in. The app’s dashboard is intuitive, making it super straightforward to track my spending and upcoming payments.
Shopping and Splitting Payments
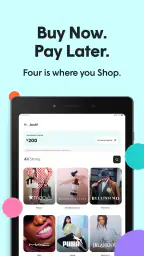
Using Four in my shopping escapades was a breeze. I simply shopped at my favorite online store, selected Four at checkout, and voilà! My purchase was split into four manageable chunks. What I particularly loved was that there were no hidden fees or interest - just pure, simple financial planning.
Why Four Stands Out
Now, you might be wondering, "What makes Four different from other buy now, pay later services?" For me, it’s the transparency and ease of use. The app sends timely reminders for upcoming payments, which is perfect for someone like me who tends to forget due dates. Plus, knowing that I won’t be slapped with unexpected charges is a huge relief.
Moreover, the support team is top-notch. I had a minor query and reached out through the app. To my surprise, the response was prompt and immensely helpful. It’s reassuring to know that help is just a message away when you need it.
The Verdict
All in all, my experience with Four | Buy Now, Pay Later has been nothing short of fantastic. Whether you’re a shopaholic or someone looking to manage finances better, this app deserves a spot on your phone. It’s like having a financial buddy that helps you make the most of your money without the stress. So next time you’re about to make a purchase, give Four a try and enjoy shopping smarter, not harder!
Frequently Asked Questions
What is Four | Buy Now, Pay Later and how does it work?
Four is a financial app that allows users to purchase items and pay for them over time, rather than upfront. Once you select the 'Buy Now, Pay Later' option at checkout with participating retailers, Four splits the total cost into smaller, interest-free payments. This flexibility makes it easier to manage finances while still obtaining necessary items without delay.
Is Four | Buy Now, Pay Later available for both Android and iOS?
Yes, Four is accessible on both Android and iOS platforms. Users can download the app from Google Play Store for Android devices and from the Apple App Store for iOS devices. The app provides a seamless experience across both platforms, ensuring users can manage their purchases and payment plans effectively, regardless of the device they are using.
Are there any fees or interest charges with Four | Buy Now, Pay Later?
Four offers its services without interest charges, making it an attractive option for those looking to avoid traditional credit costs. However, users should be aware that late fees may apply if scheduled payments are missed. It's important to understand the payment schedule and ensure funds are available to avoid any additional charges.
How does Four | Buy Now, Pay Later impact my credit score?
Using Four responsibly can have a positive impact on your credit score, as the app may report your payment history to credit bureaus. Timely payments reflect well on your credit report. However, missed payments may negatively affect your score. It's crucial to make payments on time to maintain a good credit standing.
What should I do if I encounter issues with the Four | Buy Now, Pay Later app?
If you experience any problems with the Four app, whether technical or related to your account, you should contact their customer support team for assistance. They can be reached through the app itself or via the company's website. Providing detailed information about your issue can help expedite the resolution process.


